


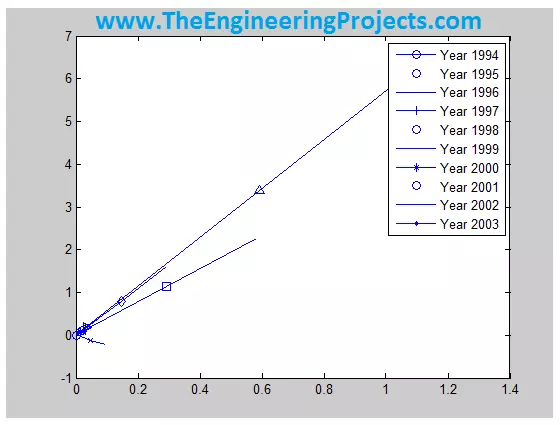
Hello friends! Today, we will work through financial calculations in MATLAB, beginning with historical market data and ending with portfolio risk-and-return plots. We will follow the original project's five stages: prepare the data, account for currency, calculate returns, estimate covariance and examine efficient portfolios. The original project compared seven market indices and explored a 3% risk-free-rate assumption. We will retain that framework, but correct several important details about exchange rates, rolling windows and portfolio interpretation. An expected return is an estimate, not a guaranteed result, and a graph is only as meaningful as the inputs behind it. This is an educational modelling example. The historical figures remain for context, while the formulas and code below e ...